First time Homebuyer
You need a partner who knows the neighborhoods, the market and the process. Who can advise you when to think on it, sleep on it or go all in on it. Because this is about much more than bricks and sticks. This is about your future home. And you don't want to live with it. You want to love it.
Second Time Homebuyer
You need a partner who knows the neighborhoods, the market and the process. Who can advise you when to think on it, sleep on it or go all in on it. Because this is about much more than bricks and sticks. This is about your future home. And you don't want to live with it. You want to love it.
The Process
Find an agent
Working with an experienced real estate agent can make all the difference. Your agent will guide you through every step of the process—searching for homes, negotiating offers, coordinating inspections, and handling the paperwork. They’ll also provide local market insight, helping you identify neighborhoods that fit your lifestyle and budget. A great buyer’s agent is your advocate, ensuring you understand each decision and helping you navigate the process with confidence.
Step 2: Get Mortgage Ready
The first step in buying a home is getting your finances in order. Review your income, monthly expenses, and credit score to understand how much you can comfortably afford. Lenders look for stable income, manageable debt, and a healthy credit profile—so pay down balances, avoid new credit cards, and correct any credit report errors. Start building your savings for a down payment and closing costs, which typically range from 2–5% of the purchase price. Having your finances organized not only helps you qualify for a mortgage but also shows sellers that you’re a serious and prepared buyer.
Step 3: Define Your Home Search
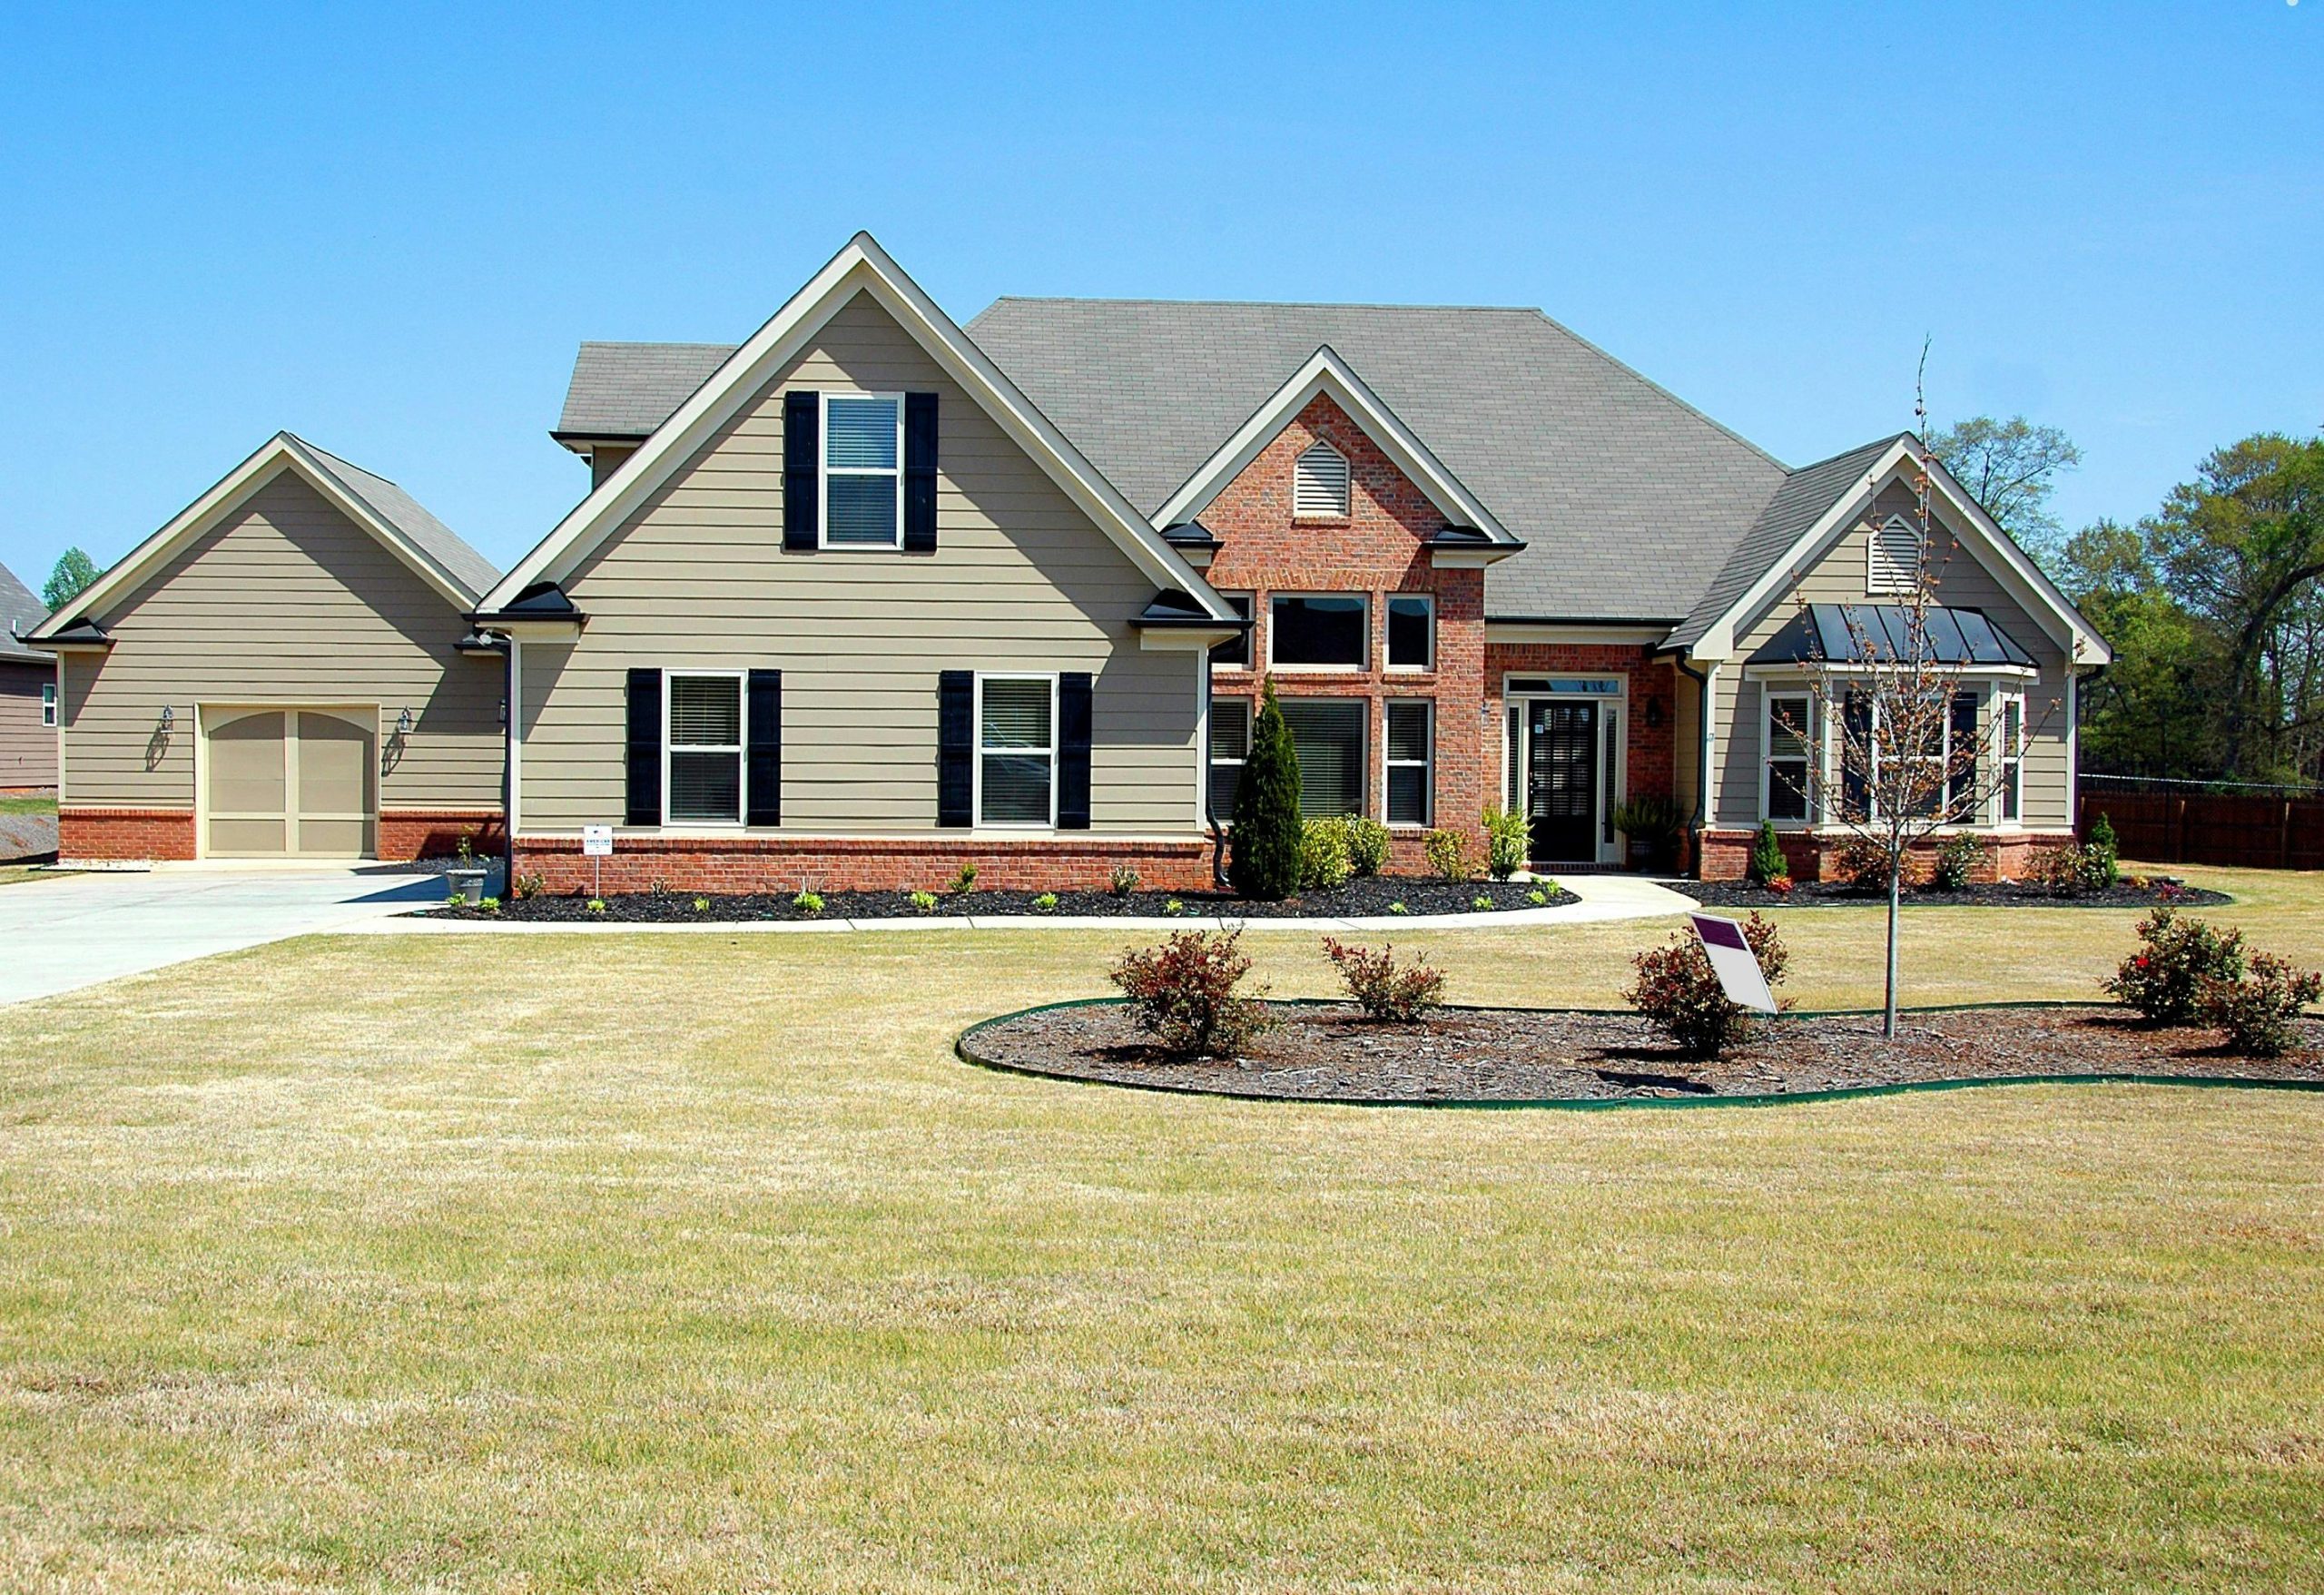
Now it’s time to clarify what you’re looking for. Create a list of “must-haves” and “nice-to-haves,” considering factors such as location, property type, number of bedrooms, layout, and amenities. Think about your long-term needs—commute times, schools, nearby parks, or potential resale value. Your agent can set up MLS alerts or show you listings as soon as they hit the market, keeping you ahead of the competition. Knowing exactly what you want helps you make quicker, more confident decisions when the right property appears.
Step 4: Tour Homes
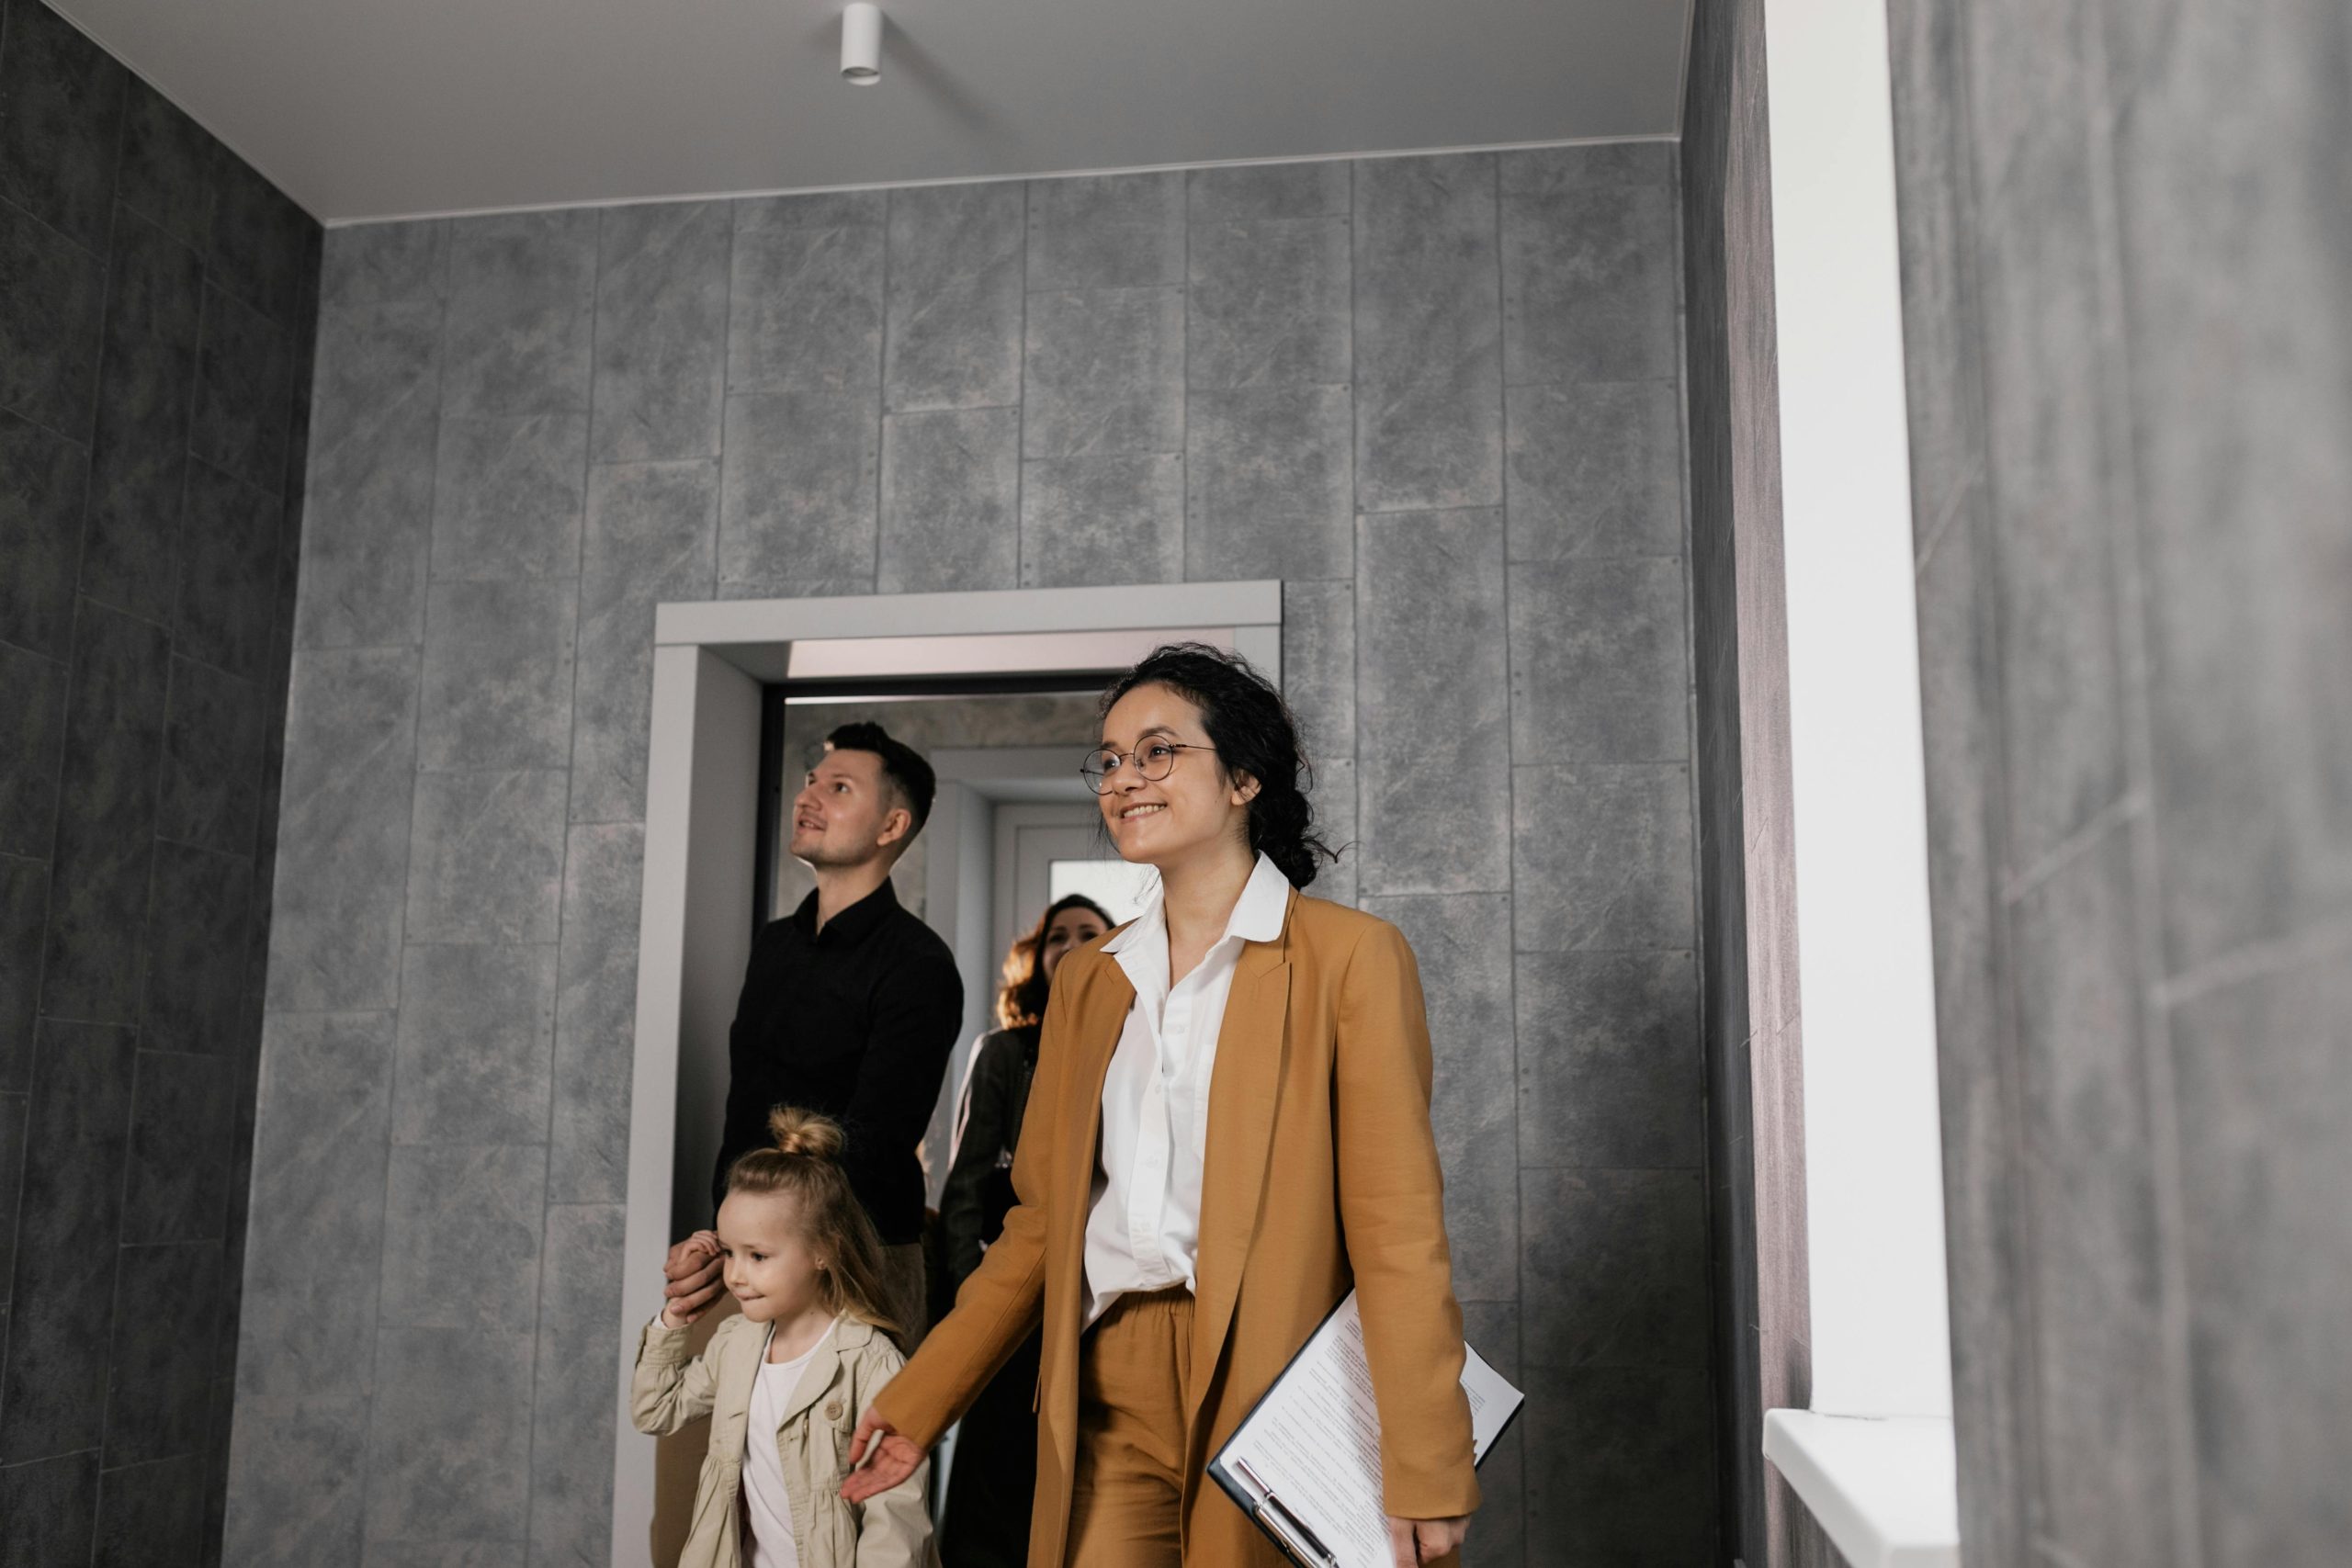
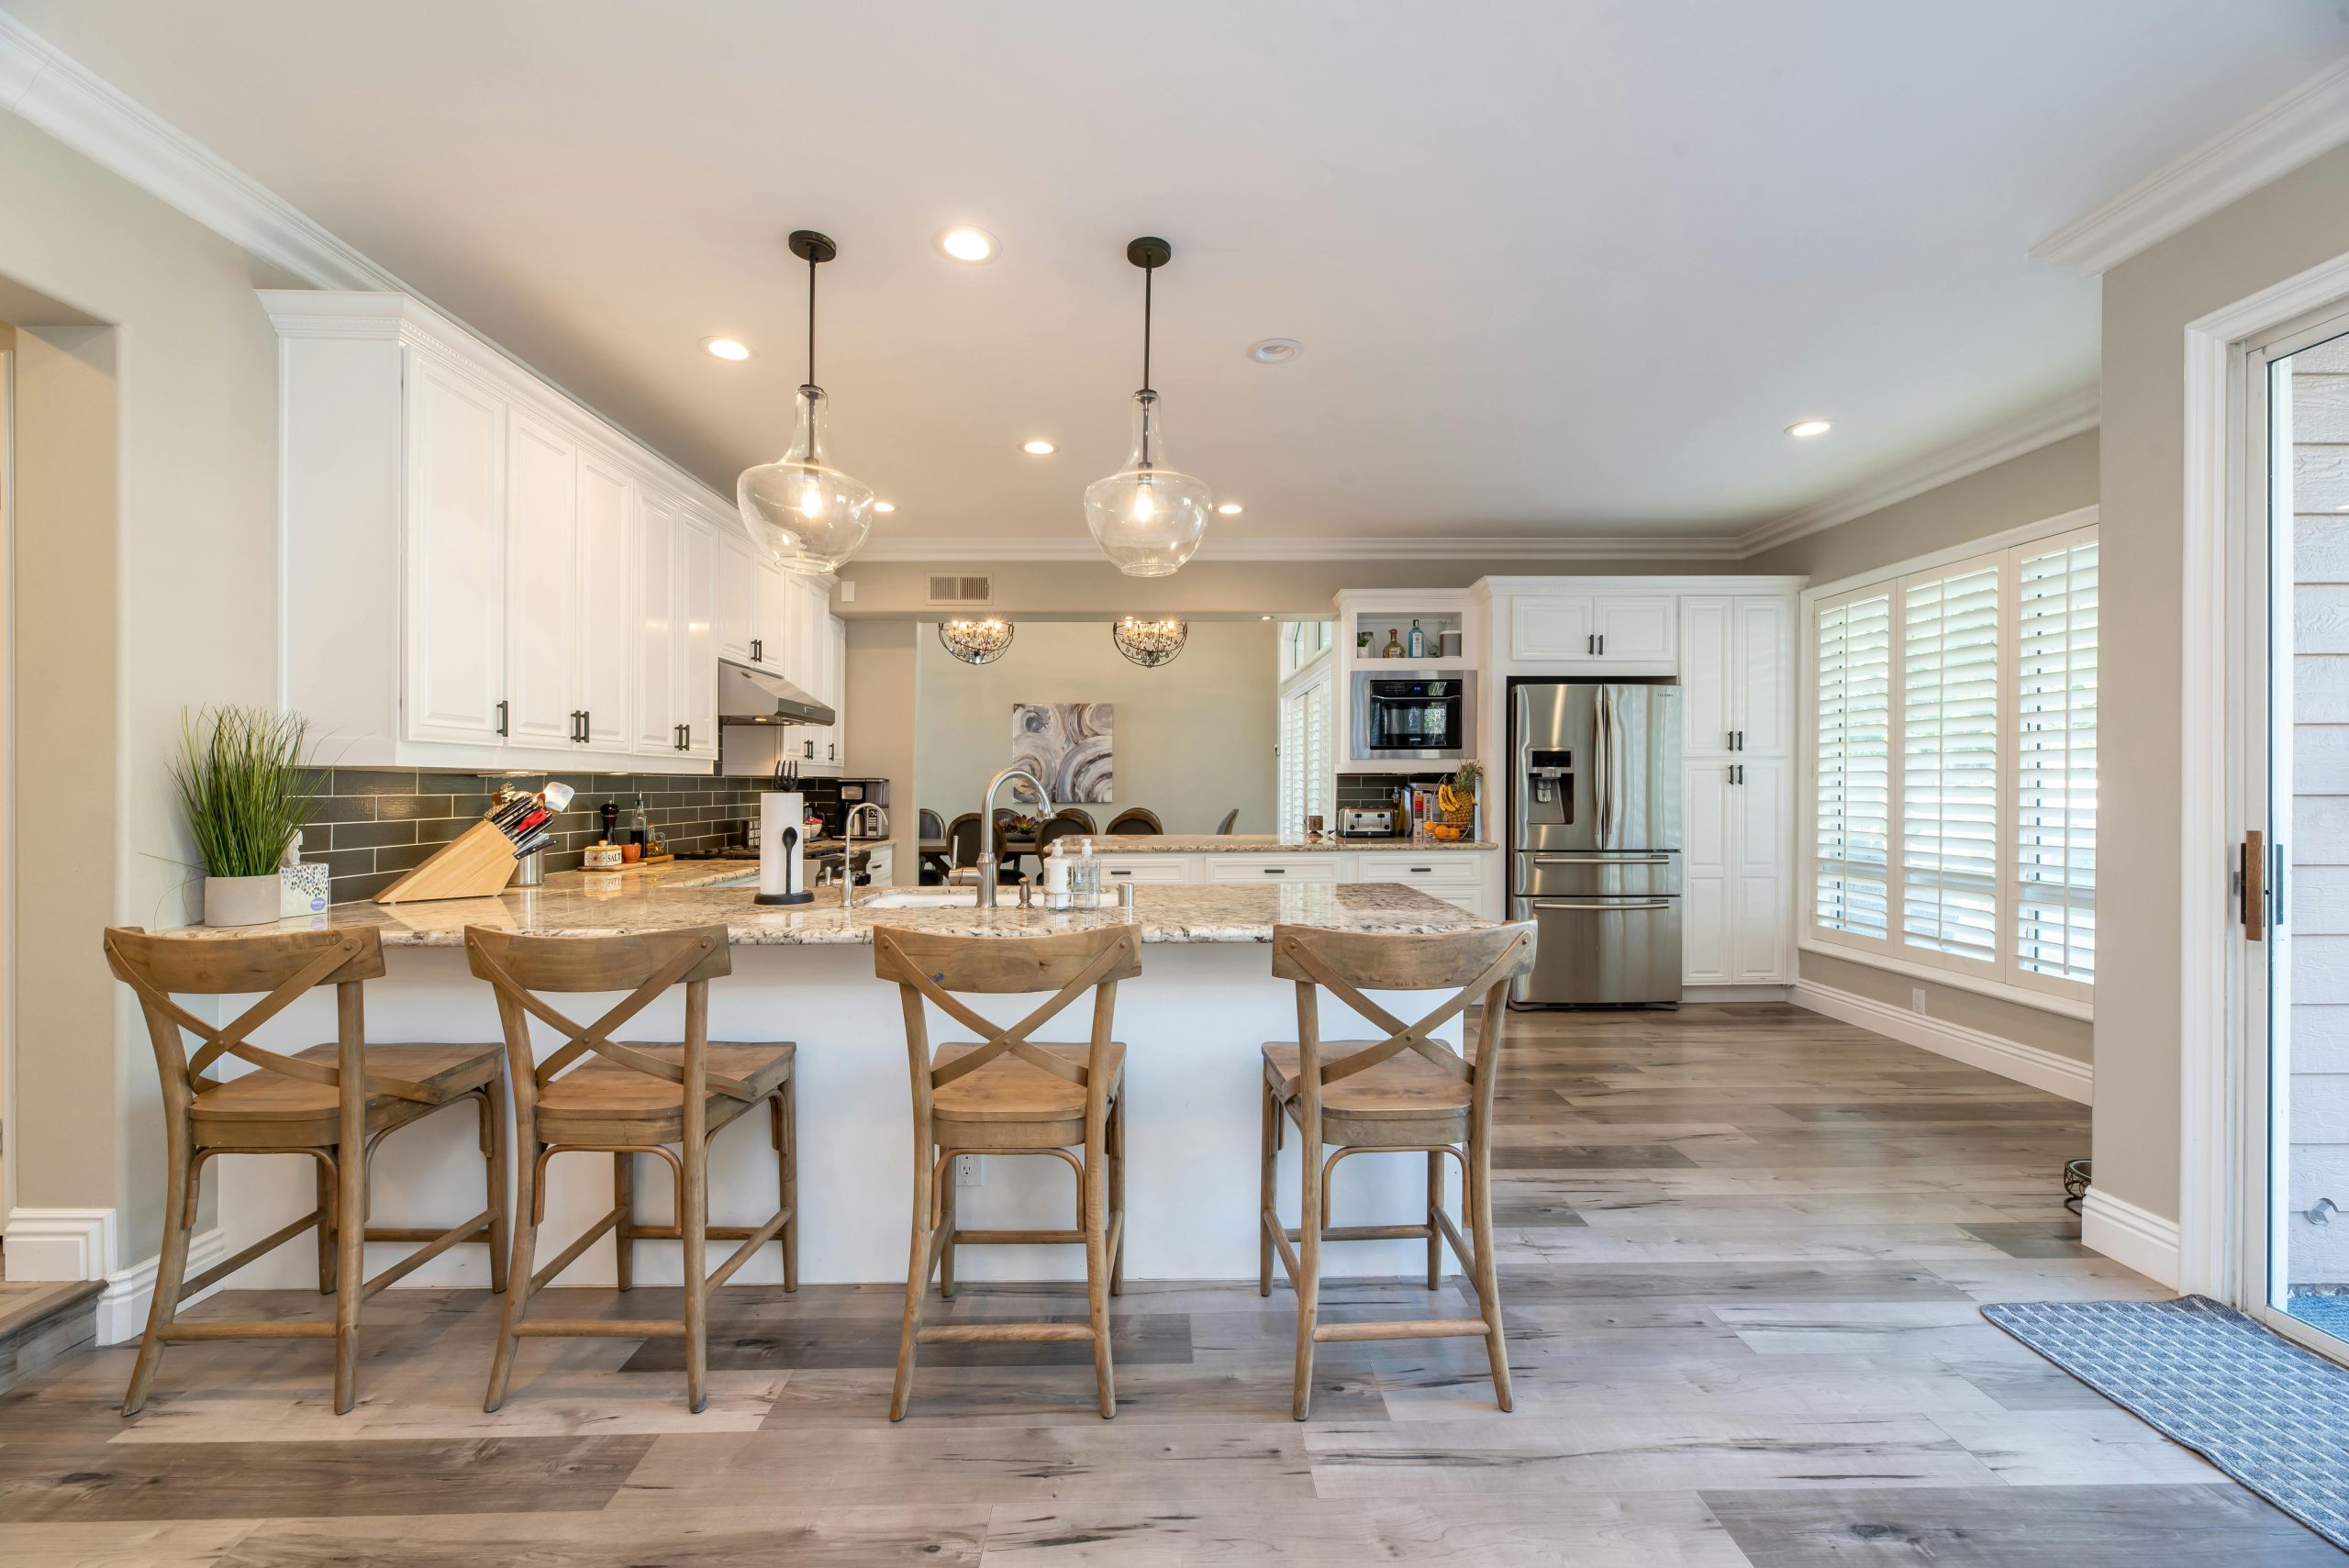
This is the fun part—seeing homes in person or virtually. Schedule showings and take notes on each property’s layout, condition, and potential repairs. Look beyond the staging to focus on essentials like structure, natural light, storage, and neighborhood noise levels. Bring your agent along to help you identify red flags and ask the right questions. Touring several homes gives you a clear sense of market value and helps you recognize a great opportunity when you see it.
Step 5: Make an Offer
Once you’ve found “the one,” your agent will help you craft a competitive offer based on comparable sales and current market conditions. Your offer will include the purchase price, earnest money deposit, contingencies (such as financing or inspections), and your preferred closing date. In a competitive market, your agent might suggest strategies like an escalation clause or shorter contingency periods to strengthen your offer. Once submitted, the seller can accept, counter, or decline—but with a solid strategy, your offer will stand out.
Step 6: Schedule Inspections & Negotiations
After your offer is accepted, you’ll schedule a professional home inspection. This step ensures there are no major issues with the property’s structure, systems, or safety. If the inspection reveals problems, you can negotiate with the seller for repairs, credits, or a price adjustment. Inspections provide peace of mind and protect your investment, helping you move forward confidently toward closing.
Step 7: Appraisal and Underwriting
Your lender will order an appraisal to confirm that the home’s value matches the agreed-upon price. If the appraisal comes in low, your agent can help you renegotiate or appeal the value. Meanwhile, the underwriting process begins, where the lender verifies your financial documents and finalizes your loan approval. During this time, avoid making major financial changes—no new credit cards, car loans, or large purchases—as these can affect your approval.
Step 8: Title Insurance
As your loan moves toward completion, a title company will conduct a title search to ensure there are no ownership disputes or liens on the property. You’ll also need to purchase title insurance to protect your ownership rights. Don’t forget to shop for homeowners insurance early—many lenders require proof before closing. Confirm your mortgage interest rate is locked in, especially if rates are fluctuating, so you don’t face any surprises before settlement.
Step 9: Review the Closing Disclosure
About three days before closing, your lender will provide a Closing Disclosure that lists your final loan terms, monthly payment, and exact cash needed to close. Review this document carefully with your agent or lender to ensure everything is accurate. This is also the time to verify your wire transfer instructions directly with the title company—never rely on emailed instructions to avoid wire fraud.
Step 10: Closing Day & Final Walkthrough
Just before closing, you’ll complete a final walk-through of the home with your agent. This is your chance to make sure any agreed-upon repairs were completed and that the property’s condition hasn’t changed since the inspection.Closing day is where all your preparation pays off. You’ll sign your loan documents, pay closing costs, and the title company will officially record the sale with the county. Once everything is processed, you’ll receive your keys and officially become a homeowner. Congratulations—you did it! Take a moment to celebrate this huge accomplishment before diving into your next to-do list.
CONGRATULATIONS
Once the final paperwork is signed, you officially become the proud owner of your new home. While it may take a few days for your mortgage lender to fund the loan, the process wraps up once the payment is delivered to the seller. After that, you’ll be ready to move into your dream home and start the next exciting chapter of homeownership.



© 2024 CENTURY 21
©2024 . All rights reserved. CENTURY 21®, the CENTURY 21 Logo and C21® are service marks owned by Century 21 Real Estate LLC. Century 21 Real Estate LLC fully supports the principles of the Fair Housing Act and the Equal Opportunity Act. Each office is independently owned and operated.
